
Executive Summary: In all five matchups between Vanguard’s active muni funds and its new index ETFs, the active managers are ahead. I rate every national and state tax-exempt fund, upgrade Short Duration Tax-Exempt Bond ETF to Buy and lay out a simple test for whether munis belong in your portfolio.
Taxes are a cost. They shrink the income and capital gains you and I get to keep, and like any cost, you want to keep them low. Municipal bonds are one way to do that.
Vanguard offers some great tax-free bond funds, and it has added several more in recent years, many with similar names. More choice has made picking the right one harder. Below, I sort through the full lineup and give you my rating on each fund.
This is the final stop in my tour of Vanguard’s bond lineup.
If you need a refresher on muni bonds, start with Muni Bonds 101.
Top Picks
Ultra-Short-Term Tax-Exempt (VWSTX): A cash alternative for money you don’t need right away.
Intermediate-Term Tax-Exempt (VWITX): The best balance of risk and return among Vanguard’s actively managed mutual funds.
Intermediate-Term Tax-Exempt Bond ETF (VTEI): The indexer’s version of Intermediate-Term Tax-Exempt.
Core Tax-Exempt Bond ETF (VCRM): Active management and broad muni-market exposure in an ETF.
Are Munis for You?
My rule of thumb: if you’re in one of the top three federal tax brackets, consider a municipal bond fund for the bond portion of your taxable brokerage account. Here’s why.
How your interest is taxed depends on whom you lend to:
- Corporate bonds: taxed at the federal, state and local levels.
- Treasury bonds: taxed federally, but exempt from state and local taxes.
- Municipal (“muni”) bonds: issued by states and local governments and exempt from federal taxes. If you live in the issuing state, the interest is typically state-tax-free, too. (There are exceptions, but let’s keep it simple.)
Since we’re talking taxes, I’m assuming you’re investing in a brokerage account. In a 401(k) or IRA, taxes aren’t an issue.
So why would anyone buy a taxable bond? Because the market is efficient enough to price in the tax break. If a muni and a comparable corporate bond paid the same yield, no one would buy the corporate bond. As a result, munis pay less.
At the end of September, Intermediate-Term Tax-Exempt yielded 4.10%. Intermediate-Term Treasury (VFITX) yielded 4.69%, and Intermediate-Term Investment-Grade (VFICX) yielded 5.69%.
To compare them on even ground, calculate the muni fund’s taxable-equivalent yield. That’s the yield a taxable fund would have to pay to leave you with the same income after taxes:
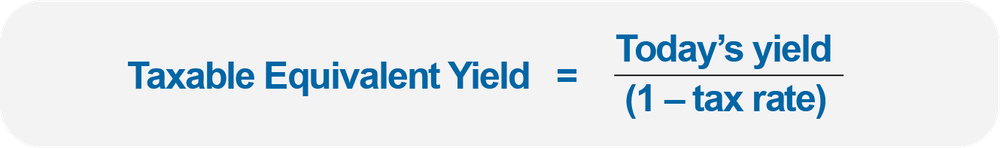
In the 35.8% bracket, Intermediate-Term Tax-Exempt’s 4.10% yield is worth 6.39% from a taxable fund, well above the Investment-Grade fund’s 5.69%. In the 24% bracket, it’s worth 5.39%, which comes up short. That’s the reasoning behind my rule of thumb.
You don’t have to run the math yourself. Each month, my Performance Review tables include taxable-equivalent yields. The table below compares Vanguard’s tax-exempt funds with their taxable siblings using end-of-September yields.
Competitive Yields on Tax-Exempt Funds
| Taxable-Equivalent Yields | ||||||||
| Yield | 22% | 24% | 35.8%* | 38.8%* | 40.8* | Yield | ||
| Municipal Money Market | 3.29% | 4.22% | 4.33% | 5.12% | 5.38% | 5.56% | Federal Money Market | 3.79% |
| Ultra-Short-Term Tax-Exempt | 3.15% | 4.04% | 4.14% | 4.91% | 5.15% | 5.32% | Ultra-Short-Term Bond | 4.51% |
| Short-Term Tax-Exempt Bond ETF | 3.31% | 4.24% | 4.36% | 5.16% | 5.41% | 5.59% | Short-Term Treasury ETF | 4.65% |
| Limited-Term Tax-Exempt | 3.53% | 4.53% | 4.64% | 5.50% | 5.77% | 5.96% | Short-Term Treasury | 4.51% |
| Short Duration Tax-Exempt Bond ETF | 3.82% | 4.90% | 5.03% | 5.95% | 6.24% | 6.45% | Short-Term Federal | 4.31% |
| Short-Term Bond ETF | 4.85% | |||||||
| Short-Term Corporate ETF | 5.26% | |||||||
| Short-Term Inv.-Grade | 5.14% | |||||||
| Interm.-Term Tax-Exempt Bond ETF | 3.89% | 4.99% | 5.12% | 6.06% | 6.36% | 6.57% | Intermediate-Term Treasury ETF | 4.89% |
| Interm.-Term Tax-Exempt | 4.10% | 5.26% | 5.39% | 6.39% | 6.70% | 6.93% | Intermediate-Term Treasury | 4.69% |
| Tax-Exempt Bond Index | 4.23% | 5.42% | 5.57% | 6.59% | 6.91% | 7.15% | Intermediate-Term Bond ETF | 5.38% |
| Core Tax-Exempt Bond ETF | 4.54% | 5.82% | 5.97% | 7.07% | 7.42% | 7.67% | Total Bond Market Index | 5.06% |
| Core Bond | 5.07% | |||||||
| Intermediate-Term Corporate ETF | 5.86% | |||||||
| Intermediate-Term Inv.-Grade | 5.69% | |||||||
| Long-Term Tax-Exempt | 4.60% | 5.90% | 6.05% | 7.17% | 7.52% | 7.77% | Long-Term Treasury ETF | 5.57% |
| Long-Term Tax-Exempt Bond ETF | 4.76% | 6.10% | 6.26% | 7.41% | 7.78% | 8.04% | Long-Term Treasury | 5.34% |
| Long-Term Bond ETF | 6.01% | |||||||
| High-Yield Tax-Exempt | 4.90% | 6.28% | 6.45% | 7.63% | 8.01% | 8.28% | Multi-Sector Income | 5.84% |
| Long-Term Corporate ETF | 6.52% | |||||||
| Long-Term Invest.-Grade | 6.17% | |||||||
| High-Yield Corporate | 6.61% | |||||||
| *Tax equivalent yields incorporate the 3.8% health care surtax into the 32%, 35% and 37% tax rates. | ||||||||
| Yields as of 9/30/2026. Source: Vanguard and The IVA | ||||||||
Tax-Sensitive Substitutes for the IVA Portfolios
If you follow one of my balanced Portfolios in a taxable account, you can make two optional swaps to opt into tax-exempt bond funds: